

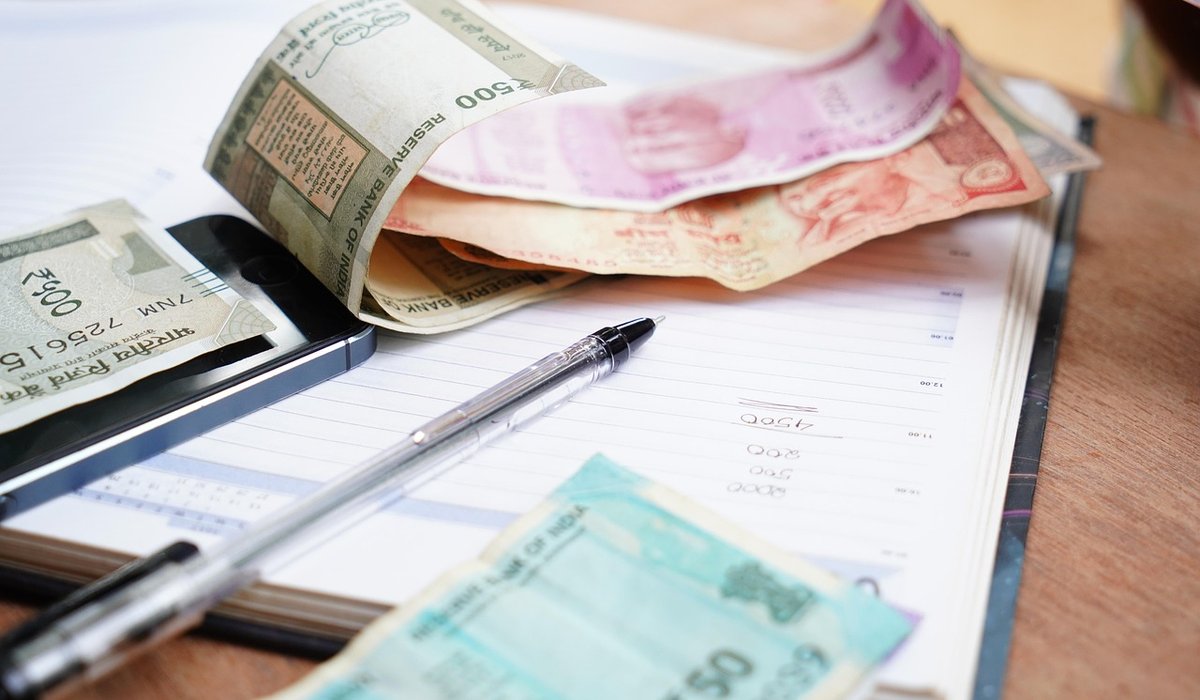
Setting Up an Emergency Fund on a Low Income
An emergency fund is not a luxury reserved for people on comfortable salaries. It is the thing that stops a broken boiler, an unexpected dental bill or a sudden cut in working hours turning into a payday loan or a credit card balance you spend two years clearing. On a low income, it is built the same way as anything else: slowly, deliberately, and with a bit of patience.
Why a Small Buffer Matters More When Money Is Tight
When there is nothing spare, every unexpected cost has to be borrowed, deferred or absorbed by cutting something you actually need. That is what makes a tight budget so exhausting. The same £300 problem that a wealthier household shrugs off can knock your whole month sideways, because you have to decide whether to miss a payment or go without heating.
An emergency fund breaks that cycle. You are not aiming for six months of expenses, which feels laughable on a low income and usually leads people to give up before they start. Aim for one bill. Then two. A fund of £500 sitting quietly in a separate account will handle most of the shocks that land on an ordinary household, and it will let you sleep.
Start With a Weekly Transfer You Will Not Miss
Weekly works better than monthly when money is tight. It matches the rhythm most households actually live by, and the amounts feel small enough to agree to.
- £3 a week is about £156 over a year.
- £5 a week is about £260 over a year.
- £10 a week is about £520 over a year.
Set up a standing order for the day after your wages or benefit payment lands, so the money leaves before you have a chance to spend it. If £3 is genuinely too much this month, start at £1. The habit matters far more than the amount during the first three months, because you are proving to yourself that saving is something you do, not something you would do if things were different.
Keep It Separate, and Just Awkward Enough
Money sitting in your current account is money you will spend. It is not a character flaw; it is how current accounts work. Open a second savings account with your existing bank, a building society or a credit union, and give it a name that means something to you. "Do Not Touch" is a perfectly good name.
Resist the temptation to attach a card to it. If withdrawing the money takes two days and a login you have not saved, you will think twice, and thinking twice is usually enough. If a separate account is not possible, draw the cash out each week and put it in a sealed envelope with the date written on the front. It is old-fashioned, but it works.
Do the Bookkeeping in Ten Minutes a Week
You do not need software or a subscription. A notebook and a page per month is enough, and it will tell you more about your money than any app you forget to open.
- Money in: wages, benefits, anything else that arrived.
- Money out: rent, energy, food, travel, debt payments.
- What is left: the number you are actually working with.
- Fund balance: what is in the emergency pot right now.
Write down every movement in and out of the fund, with the date and the reason. Two lines is plenty: "12 March, £40, car tyre." This is the single best protection against the fund quietly disappearing, because a pot nobody records is a pot nobody notices emptying.
Increase the Amount Whenever Life Gives You Room
Your income will change, sometimes for the better. When it does, resist the urge to let the extra dissolve into everyday spending. Use a simple rule: when a regular outgoing disappears, redirect at least half of it.
- A phone contract or a loan finishes, so the £25 a month goes to the fund instead.
- Council tax has two payment-free months, so that money is redirected.
- Childcare costs drop, or you pick up regular overtime, so you raise the standing order by half the difference.
- A tax rebate, a bonus or an unexpected gift arrives, so at least a third goes into the fund and the rest is spent guilt-free.
Raise the standing order by a pound rather than doubling it. Small increases stick; dramatic ones get cancelled in week three.
Decide Now What Counts as an Emergency
Define it before you need it, while you are calm and the money is not sitting there tempting you.
- Counts: an essential repair, urgent travel for a family emergency, an unexpected vet bill for a pet you own, a short gap in income, replacing a broken fridge or washing machine.
- Does not count: a sale, Christmas, a holiday, a birthday you forgot, or a deposit on something you want rather than need. Those deserve their own separate savings pots, even if each one only holds £5 a week.
If you do spend from the fund, that is not failure. That is the fund doing its job. Just restart the standing order the following week and build it back up, one small transfer at a time. A fund rebuilt at £5 a week is still a fund, and it is still more than most households have.


Budgeting
-
Use a dedicated savings account, review your budget regularly, and consider schemes that support first-time buyers in your local area.
Debt Help

-

Long established fact that a reader will be distracted
-

Long established fact that a reader will be distracted
-

Long established fact that a reader will be distracted
Saving
Karla Gleichauf
12 May 2017 at 05:28 pm
On the other hand, we denounce with righteous indignation and dislike men who are so beguiled and demoralized by the charms of pleasure of the moment
M Shyamalan
12 May 2017 at 05:28 pm
On the other hand, we denounce with righteous indignation and dislike men who are so beguiled and demoralized by the charms of pleasure of the moment
Liz Montano
12 May 2017 at 05:28 pm
On the other hand, we denounce with righteous indignation and dislike men who are so beguiled and demoralized by the charms of pleasure of the moment